










Understanding the QFC Tax Regime: Corporate Tax for QFC Entities in Doha, Qatar |
| Written by Saira Khan, Co-Founder of GMPA LLC, whose team has 15+ years of UK accounting experience advising British expats and SMEs operating across the UK and Qatar. Updated for 2026. |
| The QFC tax regime is the corporate tax framework governing firms licensed under the Qatar Financial Centre in Doha, applying a flat 10 percent tax on locally sourced profits, with defined exemptions for qualifying investment, holding, and Qatari owned entities in 2026. |
| Speak to one of our UK accountants. Book your free consultation | View Our Services |
| Key Takeaways | ||||||||
|
What Is the QFC Tax Regime?The Qatar Financial Centre operates its own tax framework, separate from the mainland regime run by the General Tax Authority. Firms licensed within the QFC in Doha are taxed under rules set out by the Qatar Financial Centre Authority, which is modelled on English common law principles and sits alongside, rather than inside, Qatar’s civil law system. This is a core reason international and British owned firms in West Bay, Lusail, and the wider Doha business community choose to register there. GMPA LLC serves clients across Doha and the wider Qatar market, and supports British expats with continuing UK tax obligations alongside their QFC commitments.
|
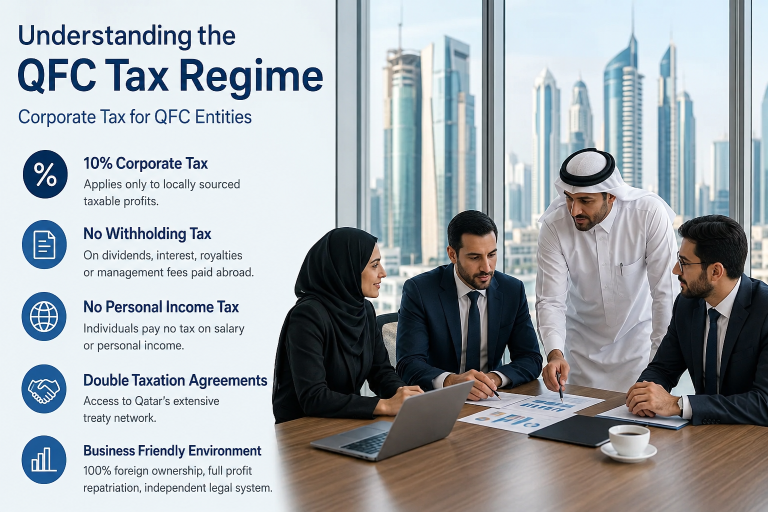
How Much Corporate Tax Do QFC Entities Pay in Qatar?Most QFC licensed entities pay a flat 10 percent tax on taxable profits that are considered locally sourced, meaning they arise from activities carried out in or derived from Qatar. Profits generated from services delivered to clients outside Qatar are generally treated as non local source and fall outside this charge, which is one of the main reasons internationally mobile firms choose a QFC structure over a mainland entity. Certain activities benefit from a concessionary 0 percent rate. This applies to investment managers, reinsurers, and captive insurers, along with entities that are at least 90 percent owned by Qatari or GCC nationals. Income from investment funds, holding companies, and Special Purpose Companies can also qualify for exemption subject to conditions. |
How Does QFC Tax Differ From Qatar’s Mainland Tax Regime?Qatar runs two parallel systems. The table below sets out the practical differences a business owner in Doha needs to understand before choosing a structure. |
| Feature | QFC Regime | Mainland Qatar (State) Regime |
| Regulator | QFC Tax Department | General Tax Authority (GTA) |
| Standard rate | 10 percent on locally sourced profit | 10 percent on taxable income |
| Foreign ownership | Up to 100 percent permitted | Foreign owned share typically taxable |
| Accounting standards | IFRS, and in some cases US GAAP, UK GAAP or AAOIFI | IFRS |
| Legal framework | English common law based | Qatari civil law |
| Tax return filing | GTA Dhareeba portal | GTA Dhareeba portal |
What Are the Filing Deadlines for QFC Corporate Tax Returns?The QFC tax year follows the calendar year by default, running from 1 January to 31 December, though firms may apply to use an alternative accounting period. Corporate tax returns are filed through the GTA Dhareeba portal, and entities with gross income exceeding QAR 500,000 must submit audited financial statements alongside the return. For a full breakdown of every annual filing obligation a QFC firm faces, see our guide to QFC annual filing requirements: a complete compliance checklist. Firms preparing for their first audit cycle often underestimate the lead time required. Our article on how to prepare your QFC firm for its first audit covers what a QFC approved auditor expects to see. |
Does Withholding Tax Apply to QFC Entities in Doha?Yes. A withholding tax applies to certain payments for services that are used or benefited from in Qatar, even where those services were physically performed abroad. This is a commonly overlooked obligation for firms in West Bay and Lusail with cross border supply chains, and it should be reviewed as part of any wider structuring decision alongside the choice between QFC and mainland status. If you are still deciding which structure suits your business, our comparison of QFC vs mainland Qatar: which is right for your business sets out the practical trade offs. |
Do British Expats in Qatar Still Have UK Tax Obligations Alongside QFC Tax?Yes, and this is one of the most misunderstood areas for British nationals running a business from Doha. Leaving the UK does not automatically end your UK tax obligations. HMRC applies the Statutory Residence Test to determine ongoing residency status, and many British expats in Qatar remain partially or wholly UK tax resident during their early years abroad, particularly if they retain UK property interests or visit the UK frequently. If you hold a UK registered company while also operating a QFC licensed entity in Doha, you face concurrent obligations across two regulatory systems at once. GMPA LLC serves clients across Doha and the wider Qatar market, and supports British expats with continuing UK tax obligations including Self Assessment filings, dividend planning, and UK corporate tax compliance, alongside their QFC commitments. |
How Can GMPA LLC Help With QFC Corporate Tax Compliance in Doha?GMPA LLC combines UK qualified accounting expertise with hands on experience of the QFC framework across Doha, The Pearl, Msheireb, and the wider GCC region. Our team prepares and files QFC corporate tax returns through the Dhareeba portal, reviews withholding tax exposure on cross border payments, coordinates IFRS compliant financial statements with a QFC approved auditor, and advises on the concessionary rate exemptions where a business structure qualifies. For a full picture of the annual compliance cycle that sits alongside your tax obligations, our guide to QFC accounts and compliance in Qatar covers filing deadlines, UBO reporting, and audit requirements in detail. |
| Frequently Asked Questions |
|
What is the QFC tax rate for corporate entities in Qatar? Most QFC licensed entities pay a flat 10 percent tax on profits sourced locally in Qatar. Certain investment, reinsurance, and Qatari owned activities can qualify for a concessionary 0 percent rate. Do QFC entities pay tax on income earned outside Qatar? Generally no. Profits considered non local source, meaning they arise from services delivered outside Qatar, typically fall outside the QFC corporate tax charge, subject to the specific facts of the business. How is QFC tax different from mainland Qatar tax? QFC entities operate under their own legal and regulatory framework based on English common law, while mainland firms fall under Qatar’s civil law system administered by the General Tax Authority. Both currently apply a standard 10 percent rate, but ownership rules, accounting standard flexibility, and exemptions differ. Do British expats in Doha still need to file UK tax returns? It depends on residency status under HMRC’s Statutory Residence Test. Many British expats in Qatar remain obligated to file UK Self Assessment returns, particularly during transition years or where UK property or income sources are retained. Where can I find official guidance on the QFC tax regime? The Qatar Financial Centre Authority publishes official tax guidance, and the General Tax Authority administers filing through the Dhareeba portal. GMPA LLC keeps clients updated on both frameworks as regulations evolve. |
| This article is intended for general guidance only and does not constitute regulated tax or legal advice. Regulatory requirements may change, so always confirm current rates and deadlines with the QFC Authority, the General Tax Authority, or a qualified adviser. Sources: Qatar Financial Centre Authority (qfc.qa), General Tax Authority Qatar (GTA), PwC Worldwide Tax Summaries. |
|
Ready to get clarity on your QFC corporate tax position in Doha?
|